Archive for the ‘Budget’ Category

Election Results: Three Propositions Go Down In Defeat

Wednesday, November 9th, 2011

The results of yesterday’s election are up, and three of the ten propositions on the ballot went down in defeat. Since all statewide propositions usually pass, that’s an interesting (and welcome) result.

  • Proposition 4, which Texans for Fiscal Responsibility said “gives counties new authority for “Kelo”-style redevelopment takings” went down by the heftiest margin, 59.7% to 40.3%.
  • Proposition 7, which would have allowed El Paso County to use property taxes to build parks, went down 51.7% to 48.3%.
  • Proposition 8, a technical amendment which allow agricultural/ranching/ etc. land to be developed for water conservation without changing its tax status, lost 53% to 47%.
  • Propositions 2 and 6 each passed narrowly with less than 52% of the vote. Proposition 1, the only one I voted for and which provided homestead exemptions for the spouses of disabled veterans, passed by the largest margin, 82.9% to 17.1%.

    Taken together, the results seem to show that Texans are actually becoming more conservative, and more willing to oppose government spending and Kelo-style eminent domain abuses.

    About 675,000 voter participated in yesterdays election.

    As a side not, notice how information on the statewide election appears nowhere on the Houston Chronicle‘s main page, though it does provide a link to how Nancy Grace did on Dancing With the Stars. Just another sign of that once great (and conservative) newspaper’s decline into being just another irrelevant liberal MSM mouthpiece.

    Reminder: Election Tuesday!

    Sunday, November 6th, 2011

    Don’t forget that there’s a state constitutional amendment election Tuesday, November 8 (as well as various local elections, bond issues, etc.). A few roundups and recommendations from:

  • Texans for Fiscal Responsibility
  • Grassroots Texans
  • The Travis County Republican Party
  • As for myself, I’m currently leaning toward voting Yes on Proposition 1 and No on all the rest.

    Blue Dot Blues has a roundup of several additional sources you can go to, including some from the other side of the aisle. When in doubt, voting against whatever the Austin Chronicle endorses will seldom steer you wrong…

    Greeks Will Not be Allowed to Vote on Their Own Future

    Thursday, November 3rd, 2011

    The scheduled referendum on the bailout of Greece as been canceled.

    Once again, the glorious dream of European integration is far to important to let details like the consent of the governed interfere…

    Rick Perry’s Tax and Spending Reform Plan: Solid on Taxes, Timid and Unserious on Spending

    Wednesday, October 26th, 2011

    So Rick Perry unveiled his tax and spending reform plan. (His Wall Street Journal piece provides a brief overview.) It’s a serious compilation of a variety of solid conservative ideas for reforming the federal government. Serious, that is, in every area except spending.

    But before we get to the sour let’s look at the sweet. There is a great deal to like in Perry’s proposals:

  • Repealing ObamaCare (though this is pretty much a requirement for every Republican office-seeker these days)
  • Repealing Dodd-Frank (which has held down the economy in many ways great and small)
  • A 20% flat tax is a vast improvement over the labyrinth complexities of our special-interest-group-carve-out-ridden Swiss cheese of a tax code. Also, you have to admire this graphic, which should have liberal knees jerking:

  • Eliminating the tax on dividends and long term capital gains is a big win that will help revive the economy and restore global competitiveness.
  • As is eliminating the death tax (although if it were possible to entirely fund the government from an estate tax rather than an income tax, that would be preferable, but it isn’t).
  • Eliminating corporate loopholes and tax breaks is also a great idea, but at this point it’s just a vague notion. Just about any candidate of any party could say the same thing, and without a list of the actual loopholes to be eliminated it’s fairly meaningless. This is also an area where few proposals survive contact with congress.
  • Reducing the corporate tax rate to 20% is a great idea, and one long championed by many free market economists.
  • The Perry plan has a lot of good ideas for reducing the regulatory burden on American business. A moratorium on all pending legislation, automatic sunset provisions, and a full audit of all regulations enacted since 2008 should go a long way toward undoing the Obama regulatory burden and getting American business and hiring back on track.
  • So outside of the budget provisions, there is an awful lot for conservatives to like about the Perry plan.

    Even when it comes to the budget section, there’s a lot of conservative red meat: a non-tax hike balanced budget amendment, an end to baseline budgeting and concurrent resolutions (which bake bigger government into the process), and an end to earmarks. All solid initiatives, though the problem here is less presidential will than getting them through congress.

    So, given all that, what am I complaining about?

    What makes the Perry budget timid and unserious is his proposal to “balance the budget by 2020.” Given the way Washington works, a promise to balance the budget eight years from now is a promise to never balance the budget. It’s tea so weak it might as well be water. A balanced budget target that far out means that Congress can keep putting off difficult decisions by passing bills that place imaginary savings in out years where they will soon be rendered moot by the next congress. It’s once again a chance to sell out budget discipline for a handful of magic beans.

    It’s, yet again, kicking the can down the road.

    It’s also a big step back from the Ryan plan, which demanded a balanced budget in the 2015 timeframe. This was the plan seen by conservative Republicans and Tea Party activists as the minimum necessary for a serious reduction in the federal budget deficit. Given serious action wasn’t taken for it this year, it’s reasonable to push it that deadline out one more year to 2016, but pushing the target out beyond that amounts to preemptive surrender.

    While Perry’s $100 billion first year down-payment would be an improvement over the weak, phony-baloney deficit reduction enacted as part of the debt limit deal, it’s a ridiculously small cut for the $1 trillion+ Obama deficits being racked up each fiscal year.

    Bad as it is as policy, the Perry 2020 date is utterly disasterous as an opening position for negotiations with congress. Perry is going to have to set hard, early deficit targets to have any chance of taming the Leviathan, and then use his veto pen early and often if he doesn’t get them. The truth is that Democrats will scream bloody murder at any attempt at deficit reduction, so the next President might as well (to use the classic Ronald Reagan analogy) “throw long.” Every debt ceiling vote will have to come with both serious budget cuts and the other budget-taming proposals in the Perry plan. Democrats may still filibuster, but then they’ll have to deal with the crushing realities of living under a budget that actual matches spending to revenues. Even with a Republican House and Senate, to actually balance the budget the next President will need to push relentlessly to pass the most stringent budget that can muster 51 senator votes via reconciliation. Setting a 2020 date does nothing to prepare the media and ideological battlespaces for those difficult choices.

    Out-of-control federal spending is at the heart of almost all our economic problems, and the single biggest factor behind Tea Party discontent. Thus it has to be at the top of the next President’s agenda. Despite many other solid economic idea, the Perry plan doesn’t meet the test for serious deficit reduction. The shame is that Perry accomplished real spending reform in Texas. To impose such discipline on the out-of-control federal budge will be an order of magnitude more difficult. But to achieve real spending reform, you first have to campaign for it. Setting a goal for a balanced budget at the end of a theoretical Perry presidency’s second term rather than the first actually hampers that goal.

    LinkSwarm for October 25, 2011

    Tuesday, October 25th, 2011

    Have a nice cup of randomness:

  • Post-Gadhafi Libya will be run as an Islamic state under Sharia law. Thanks a lot for that great foreign policy triumph, Obama.
  • This Islamsists also came out on top in the election in Tunisia. Maybe the Arab Spring version of democracy will turn out to be the same kind that came to Post-Colonial Africa in the 50s and 60s: One Man, One Vote, Once. Liberals were big cheerleaders then, too.
  • Mickey Kaus points out that propping up public sector employment is a lousy idea even in Keynesian. But it’s a great idea if you want to keep Democrats in power as part of an ever-expanding government, thus providing even more opportunities for graft and kickbacks, as well as back-scratching campaign contributions from public sector unions. Which is probably the real reason Matthew Yglesias is so gung-ho for the idea. Or, as Alpha commenter Peter Schaeffer notes below Yglesias’ original post: “This isn’t about stimulating the economy, but providing slop to the public sector trade unions that dominate the Democratic party.”
  • NPR host fired for overtly acting as a liberal mouthpiece rather than covertly. Which is why the host of All Things Dismembered stepped down because of her husband’s job with the Obama campaign. Maybe NPR staffers need a refresher on their “We all work for the Democratic Party, but here’s how to hide it” orientation course…
  • Why people are moving to the South: “Ask transplanted business owners and they’ll tell you they like investing in states where union bosses and trial lawyers don’t run the show, and where tax burdens are low. They also want a work force that is affordable and well-trained. And that doesn’t see them as the enemy.”
  • Red State, Blue State

    Sunday, October 16th, 2011

    Tax revenues in Texas rose 11.8% in September compared to September a year ago.

    Meanwhile, California took in 4 percent less than anticipated in September, falling $300 million short in September alone and $700 million short for the year.

    These numbers offer me a chance to offer up my long-in-gestation comparison between Texas and California.

    Both Texas and California share a number of similarities: They are the two most populous states in the Union, both are southern states with warm climates, both have long coastlines and important ports handling international trade, both share a border with Mexico, both have diverse populations and diversified economies, including extensive portions of the agriculture, energy, and high tech sectors.

    The biggest difference between the two is their respective governments. Texas, of course, is the paragon of the red state model (low tax, low spending, limited government, non-union) whereas California is the classic example of the blue state model (high tax, high spending, expansive welfare state, closed shop). Texas kept government small, tightened its belt and lived within its means. California spent like there was no tomorrow, jacked tax rates into the stratosphere, and gave generous contracts to public employee unions. Now Texas is doing well and California is going broke.

    Jay Ambrose asks:

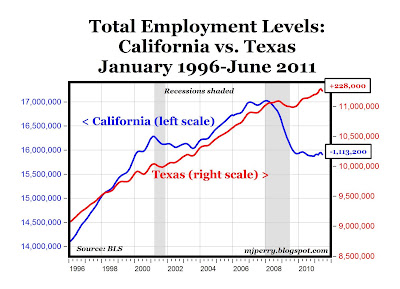
    So what example should America follow, that of deficit-slaughtering, budget-cutting, seriously limited government in Texas, which has added 730,000 jobs in the past decade, or that of regulation-happy, spend-mercilessly, owe-everything, flee-this-place-quickly California, which has lost 600,000 jobs during the same period?

    Texas has some of the best cities for jobs in the country. California? It “boasted zero regions in the top 150.”

    Chief Executive ranks Texas as the best state for business, and California as the worst.

    High tech companies are fleeing California for low tax states. In fact, high earners inevitably flee high tax states for low tax states:

    Examining IRS tax return data by state, E.J. McMahon, a fiscal expert at the Manhattan Institute, measured the impact of large income-tax rate increases on the rich ($200,000 income or more) in Connecticut, which raised its tax rate in 2003 to 5% from 4.5%; in New Jersey, which raised its rate in 2004 to 8.97% from 6.35%; and in New York, which raised its tax rate in 2003 to 7.7% from 6.85%. Over the period 2002-2005, in each of these states the “soak the rich” tax hike was followed by a significant reduction in the number of rich people paying taxes in these states relative to the national average. Amazingly, these three states ranked 46th, 49th and 50th among all states in the percentage increase in wealthy tax filers in the years after they tried to soak the rich.

    Here’s a comparison between California and Texas that explains, in great detail, how and why Texas is kicking California’s ass. Remember those job creation numbers, so ably depicted by WILLisms?

    Now compare Texas to California via this chart from Mark J. Perry’s Carpe Diem blog:
    Another reason Texas is thriving is that it doesn’t have overpaid, all-powerful public sector unions.

    High tech employees are fleeing California for Texas, because they can keep more of what they make, the government isn’t going bankrupt, and the roads and schools are now better in Texas. Despite all the money California spends on a a bloated public sector, the actual core services delivered are worse in California than they are in Texas:

    “Today, you go to Texas, the roads are no worse, the public schools are not great but are better than or equal to ours, and their universities are good. The bargain between California’s government and the middle class is constantly being renegotiated to the disadvantage of the middle class.”

    Just how broke California is became apparent in a recent Michael Lewis piece in Vanity Fair. It illustrates who irretrievably broken California’s politics and finances are, and just how little a dent Gov. Arnold Schwarzenegger made in fixing the problem:

    David Crane, the former economic adviser—at that moment rapidly receding into the distance—could itemize the result: a long list of depressing government financial statistics. The pensions of state employees ate up twice as much of the budget when Schwarzenegger left office as they had when he arrived, for instance. The officially recognized gap between what the state would owe its workers and what it had on hand to pay them was roughly $105 billion, but that, thanks to accounting gimmicks, was probably only about half the real number. “This year the state will directly spend $32 billion on employee pay and benefits, up 65 percent over the past 10 years,” says Crane later. “Compare that to state spending on higher education [down 5 percent], health and human services [up just 5 percent], and parks and recreation [flat], all crowded out in large part by fast-rising employment costs.” Crane is a lifelong Democrat with no particular hostility to government. But the more he looked into the details, the more shocking he found them to be. In 2010, for instance, the state spent $6 billion on fewer than 30,000 guards and other prison-system employees. A prison guard who started his career at the age of 45 could retire after five years with a pension that very nearly equaled his former salary. The head parole psychiatrist for the California prison system was the state’s highest-paid public employee; in 2010 he’d made $838,706. The same fiscal year that the state spent $6 billion on prisons, it had invested just $4.7 billion in its higher education—that is, 33 campuses with 670,000 students. Over the past 30 years the state’s share of the budget for the University of California has fallen from 30 percent to 11 percent, and it is about to fall a lot more. In 1980 a Cal student paid $776 a year in tuition; in 2011 he pays $13,218. Everywhere you turn, the long-term future of the state is being sacrificed.

    It’s even worse at the local level, where cities are going broke do to outrageous union pensions, such as in San Jose:

    It shows that the city’s pension costs when he first became interested in the subject were projected to run $73 million a year. This year they would be $245 million: pension and health-care costs of retired workers now are more than half the budget. In three years’ time pension costs alone would come to $400 million, though “if you were to adjust for real life expectancy it is more like $650 million.” Legally obliged to meet these costs, the city can respond only by cutting elsewhere. As a result, San Jose, once run by 7,450 city workers, was now being run by 5,400 city workers.

    What do the citizens of California get for some of the highest public sector wages in the country? Police and firefighters that stand around watching a man drown.

    San Jose is far from the worst:

    Back in 2008, unable to come to terms with its many creditors, Vallejo declared bankruptcy. Eighty percent of the city’s budget—and the lion’s share of the claims that had thrown it into bankruptcy—were wrapped up in the pay and benefits of public-safety workers.

    California has some of the highest taxes in the country, and it can’t make ends meet because it’s welfare state and public employee unions suck up every available dollar and more.

    You cannot tax your way to prosperity.

    You cannot spend your way to prosperity.

    Government can only create the conditions that allow the free market to create jobs.

    The red state model works.

    The blue state model doesn’t.

    Obama by the Numbers

    Tuesday, October 4th, 2011

    Well done, and in convenient video form. Put together by the folks at Minnesota Majority, based on original work by the folks at Ace of Spades.

    “Greece is not salvagable”

    Friday, September 30th, 2011

    That’s the rather bracing judgment from this Stratfor overview of Greece’s problem. Moreover, they’re saying that about its existence as a nation-state, even absent the European debt crises. Also: “Greece has to be kicked out of the Eurozone if the Eurozone is to survive.” Problem? They don’t have enough “firebreak” funds to do it. “Until the Europeans have 2 trillion Euro in funding stashed away, they can’t kick Greece out of the system.”

    I’m not sure I share the pessimism about Greece in the long run. After all, nation-states can exist for an awful long time, despite crappy conditions (see, for example, Haiti). Of course, that assumes that a newly Islamic Turkey doesn’t decide to settle old scores by conquering them outright. (Assuming, of course, that Turkey is still predominately Turkish rather than Kurdish. Claire Berlinski is a little more sanguine about that prospect.)

    Honestly, of the two, I think Greece will outlast the Eurozone by a good measure. The question isn’t the whether Eurocrats can prevent the Eurozone from breaking up, but rather how long they can delay the inevitable, how much sovereign debt can they put taxpayers on the hook for, and how much harder will the inevitable market correction be when it comes? It seems to be a race between how much European taxpayer money can be wasted propping up Europe’s bankrupt welfare states vs. how much of American taxpayer money can the Obama administration waste channeling payouts to well-connected Democratic cronies. The Eurocrats may be winning the race to insolvency, if only due to the lack of a European Tea Party.

    In other Euro Debt Crises news:

  • Europe votes to throw more money down the rat hole.
  • But don’t take that as any kind of victory for the Euro. Quite the opposite. “The furious debate over the erosion of German fiscal sovereignty and democracy – as well as the escalating costs of the EU rescue machinery – has made it absolutely clear that the Bundestag will not prop up the ruins of monetary union for much longer. Horst Seehofer, the leader of Bavaria’s Social Christians, said his party would go ‘this far, and no further’.”
  • Greece passes the tax increase the Eurocrats say is necessary to stave off default.
  • How broke is Europe? They’re considering a tax on every financial transaction. This is great news…for stock exchanges outside of Europe.
  • How Charles de Gaulle foresaw the Euro crackup.
  • The German finance minister says that a leveraged Euro-TARP is dead. I would say why U.S. regulators were pushing such a scheme was puzzling, except of course it isn’t. The goal is to put off the Euro-collapse until after the 2012 elections.
  • Meanwhile, liberal moneybags mastermind George Soros says that the Euro crises is dragging us toward another depression. His solution? I know you’re going to be shocked, shocked to learn that it’s bigger, more central government. “The governments of the eurozone must agree in principle on a new treaty creating a common treasury for the eurozone. In the meantime, the major banks must be put under the direction of the European Central Bank.” To be followed shortly thereafter by the formation of the First European Airborne Swine Squadron.
  • Is there any other place desperate Eurocrats can get money to prop up their falling welfare states? Are they perhaps hoping that Obama will bail them out? After all, what’s a few more trillions in unsupported debt between friends?

    More Greek Default Rumblings

    Sunday, September 25th, 2011

    Actually, less rumblings than the roar of an approaching train. And since I temporarily seem to be ahead of the latest Ace of Spades Doom roundup, I’m going to try and give you a nice clear view of the coming crash.

    “No longer a question of if, but when – that is the tone of discussions over Greece which has dominated the summit of finance ministers in Washington over the weekend.” Former Britain’s former finance minister Alistair Darling agrees, calling default “only a matter of time.”

    The talk now is of how to put in a “firewall” to prevent the contagion of an inevitable Greek default from spreading throughout the European banking system.

    The Euroskeptics have been completely vindicated:

    Very rarely in political history has any faction or movement enjoyed such a complete and crushing victory as the Conservative Eurosceptics. The field is theirs. They were not merely right about the single currency, the greatest economic issue of our age — they were right for the right reasons. They foresaw with lucid, prophetic accuracy exactly how and why the euro would bring with it financial devastation and social collapse.

    I think at this point UK residents should be feeling vrey glad indeed that they didn’t abandon the Pound for the Euro.

    Bret Stephens talks about the long line of deceit and fraud that lead Europe to the current crises. “What is now happening in Europe isn’t so much a crisis as it is an exposure: a Madoff-type event rather than a Lehman one.”

    Mark Steyn, using the ever popular music and political metaphor gambit, compares the breakup of the Eurozone with the breakup of R.E.M. while bringing the usual Steyn goodness: “Attempting to postpone the Club Med welfare junkies’ rendezvous with self-extinction will destabilize internal German politics (which always adds to the gaiety of nations).” And this:

    As its own contribution to the end of the world as we know it, the Obama administration has just released a document called “Living Within Our Means and Investing in the Future: The President’s Plan for Economic Growth and Deficit Reduction.” If you’re curious about the first part of the title — “Living Within Our Means” — Veronique de Rugy pointed out at National Review that under this plan debt held by the public will grow from just over $10 trillion to $17.7 trillion by 2021. In other words, the president’s definition of “Living Within Our Means” is to burn through the equivalent of the entire German, French, and British economies in new debt between now and the end of the decade. You can try this yourself next time your bank manager politely suggests you should try “living within your means”: Tell him you’ve got an ingenious plan to get your spending under control by near doubling your present debt in the course of a mere decade. He’s sure to be impressed.

    Germany is near the limit of their willingness to bail out Greece.

    There may even be a taxpayer revolt brewing in the Aegean.

    And if the other PIIGS are doing better than Greece, it is only a matter of degrees: “Italy is the new Lebanon, Portugal the new Venezuela, Spain the new Vietnam, Ireland the new Argentina and nothing is more risky than Greece, according to today’s credit default swap market.”

    But it’s not just Greece and Europe that are hitting the wall. China’s housing bubble may finally be bursting. Worse still: “growth in China may be zero [and] China has ‘European kind of numbers’ when it comes to debt.”

    And the Chinese housing bubble isn’t just affecting China. It’s also affecting Canada.

    And at least one observer has drawn parallels to a certain hopemonger currently residing in the White House:

    Obama has no intention of really solving the debt crisis. And that brings us back to Greece. That government has been doing the same thing for a decade and the chickens have now come home to roost. Greece’s debt is 150 percent of its Gross Domestic Product. Our debt has just reached 100 percent of GDP and the debt is accumulating faster than it ever has. If we were looking out the windshield down the road, we could see the crash that’s just up around the bend.

    But rather than put on the brakes, the president has chosen to pick a fight with the other passengers in the car he is driving. Talk about distracted driving! He is gambling that this fight will convince the passengers to let him stay behind the wheel for another four years. But we certainly can’t wait that long. He’s turned up the radio in hopes we won’t hear the ambulance sirens.

    It looks like its going to be another rough week for world markets…

    Greece Getting Ready to Default?

    Monday, September 12th, 2011

    According to Seeking Alpha last week: “Yields on two-year Greek government bonds reached 46.84% recently. This is roughly comparable to yields on Argentine bonds in early December 2001 – only a month before the country defaulted on its debt.”

    Other signs of the Euro crisis: The Euro hit a six month low against the dollar, and a ten year low against the yen.

    Now Walter Russell Mead is reporting that markets around the world have a serious case of the jitters due to the possibility of a European meltdown. “Creating a monetary union without a true federal government is looking more and more like the biggest European policy mistake since Britain and France let Hitler have the Sudetenland.”

    It’s not just Greece. Investors are now worrying about the potential solvency of French banks.

    Last week, Powerline linked to this cheerful piece over at Zero Hedge, which outlines some consequences of a Euro breakup: “Were a stronger country such as Germany to leave the Euro, the consequences would include corporate default, recapitalisation of the banking system and collapse of international trade.” Lovely. Other possibilities: The rise of authoritarian or military governments to contain the crisis, or civil war.

    Despite all this, the EU itself, when not pushing for further austerity, denies it’s preparing for a Greek default. Should we be more worried that the Eurocrats running the show are liars or idiots?

    Here’s Peter Morici calling Greece to default and abandon the Euro, although comically, he’s saying that it’s Greece that is the exploited nation “at the mercy of Germany and other rich states who exploit European unity to live well at the expense of their poorer brethren.” Of course this is an inversion of the actual situation, with wastrel cousin Stavos living high on the hog off of Uncle Fritz and Aunt Helga’s credit rating.

    But that might be coming to an abrupt end. Despite a slew of austerity measures introudced over the weekend, the Greek government only has enough money to last through the middle of October. There are technical obstacles to still more bailouts from Germany, assuming Uncle Fritz was even willing to extend more credit. Signs are that he isn’t. Indeed, German Chancellor Angela Merkel is openly discussing “an orderly bankruptcy of Greece.” The bond market is already treating a Greek default like a near certainty. It seems like the plan to prop up Greece until banks can stick European taxpayers with the bill may be coming undone.

    So, you think gold prices would soar, right? Wrong. “Gold futures slumped as traders cashed out of the perceived refuge asset to cover losses in other markets while Europe’s debt crisis seemed poised to take a turn for the worse.” So it’s gotten so bad that traders need to sell gold in order to cover losses in everything else but gold.

    Hang on, folks. We could be in for a very rough ride…