Greece shuts down its bloated, money losing ERT public television/radio network. “Problems with Greek democracy are not the reason that ERT was shut down. ERT was an extravagant public company. Many, though not all, employees were hired under suspicious conditions, due to favoritism and nepotism, and receiveddisproportionately large wages (8000 Euros per month through the financial crisis and 13000 Euros per month before).”
Taki (who is Greek) offers some pungent assessments of his home country’s continual crisis.
In Europe, the law is seen is “an obstacle rather than a foundation.”
So Greeks head off to the polls this weekend to (theoretically) choose whether to muddle along with a “right” (for Greece) government that will actually attempt to carry out something vaguely resembling austerity, or for Alexis Tsipras’ far-left Syriza party, who intends to re-enact Clevon Little’s scene from Blazing Saddles: “Drop the austerity demands, or I’ll drop out of the Euro and refuse to let Germany bail us out anymore!” “Do what he says, do what he says, that Greek’s crazy!” It’s anybody’s guess whether Greece will opt to keep the farce going for another few months, or finally set the whole house of cards tumbling down.
My guess is that there are still enough insiders who can benefits from dumping PIIGS bonds onto various sets of European taxpayers, so I expect that, one way or another, the Eurocrats will find a way to keep the charade up for another two or three months.
In light of that, here’s a roundup of Euro debt news:
How the Euro will end: “Greece will simply run out of cash. Then Spain’s real-estate bubble will ruin an economy that really matters.”
Still not completely depressed about Europe’s prospects for escaping the trap created by their bankrupt cradle-to-grave welfare states? Well then, here’s some Mark Steyn to cruelly stomp on those last flickering embers of hope.
How about a nice slice of EuroDoom to ease you into the weekend?
With all the post-primary news, the European Debt Crises news has been chugging along for a while now. let’s look at some, shall we?
Heh. “The Euro cannot be destroyed by any craft that we here possess. It was made in the fires of Frankfurt. Only there can it be unmade. It must be taken deep into the heart of the European Central Bank, and cast back into the fiery chasm from whence it came!”
If the Leftists win the next round of voting in Greece, they promise to cancel the EU-sponsored bail-out and re-nationalize banks and companies. Way to calm the markets, dude! Not to mention reenacting Clevon Little’s famous scene from Blazing Saddles. “Experience is a dear teacher, but fools will learn from no other.”
It’s a winner-take-all world. Countries that do well have to do a few things extremely well. Germany makes the world’s best machine tools, some of the best heavy engineering equipment, not to mention autos. German manufacturing dominates innumerable key niches. The Spanish don’t do anything well. They haven’t done anything well since the Spanish Empire outsourced its manufacturing to Flanders in the 16th century.
As a journalist told me yesterday, he worries whether the money in his pocket will be worth anything a year from now. Others worry about Germany’s increasingly negative image among recession-hit southern and eastern Europeans. Americans will understand this feeling well: you pay and pay to help others, only to have them turn on you in hatred and wrath, accusing you of horrible hidden motives and denouncing your selfishness.
All sorts of stories bubbling away in various states of completion. In the meantime, here’s a nice Saturday LinkSwarm that includes some (but not all) of the links I’ve put up on my twitter feed:
We’ve gotten use to Democratic office holders in Texas switching to the Republican Party, but I don’t think we’ve ever seen all the Democratic officeholders in a county switch at the same time, which is what just happened in Throckmorton County, including the sheriff, county judge, clerk, treasurer, justice of the peace and three commissioners.
Texas Democrats give up on Texas Democrats. “Of the $21 million Texas Democrats have given to candidates running for federal office, Super PACs and party political committees in the 2012 election, only $4.8 million has gone to candidates from Texas.”
Today’s Texas Democrat under federal investigation for corruptions comes to you from Cameron County DA Armando Villalobos, who’s also running for U.S. congress in the newly created 34th congressional district.
Chances are good that Europe’s interesting Eurozone times are about to get more interesting still with elections scheduled across the continent today, including those in France and Greece. So what does all this mean? Well, for one thing, the French socialist candidate (who has a good chance to kick Nicolas Sarkozy out of office) wants to renegotiate the fiscal discipline treaty. Perhaps even a socialist can tell a rotting fish when he smells one. And in Greece, the anti-bailout parties are expected to make dramatic gains at the expense of the “center-right” New Democracy (Tweedledee) and “center-left” Pasok (Tweedledum) parties who managed to bring Greece to this lovely pass in the first place.
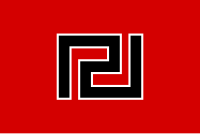
Opposing Tweedledee and Tweedledum are a motley collection of small parties, including the Neo-Nazi Golden Dawn. Now in Europe, everyone to the right of the Christian Democrats seems to be labeled a “neo-Nazi,” be they libertarians, Geert Wilders, or the British National Party, but Golden Dawn appears to be the real thing. Take a look at their flag:
The overall color scheme seems vaguely familiar. Where have I seen that before? Let me think…
Of course, Golden Dawn is unlikely to gain enough votes to be a real player in the Greek parliament, so we may be denied the irony of seeing neo-Nazis oppose Greece’s German overlords.
There are also elections in Serbia and Armenia, lower level elections in Italy, and in Germany, regional elections in Schleswig-Holstein. While “regional elections in Schleswig-Holstein” must be almost as exciting a topic to American readers as enhanced rescission authority, it might go a long way toward determining whether Angela Merkel will continue in her role as Europe’s Sugar Momma Dominatrix.
Could the ruling parties lose everywhere? Well, since the ruing parties have collectively lost every single election since 2009, yeah. Now, whether the Eurocratic elite are will to let a little thing like “democracy” derail their dreams for an integrated Europe remains to be seen.
With government debt expected to hit 80% of GDP by the end of 2012, Spain has become like a family with a big mortgage where the primary breadwinner has lost his job. Unless they find a way to increase their income, they are going to go bankrupt. It is only a matter of time.
If people want to know what life looks like in the “Prohibitive Range” of the Laffer Curve, all they have to do is to visit Athens. Greece is literally falling apart. Unfortunately, by raising taxes, Spain is making exactly the same mistake that the Greeks made.
Of course, whatever the outcome of today’s elections are, we can be pretty sure they won’t do the one thing that might help get them out of the crises: rolling back the European welfare state.
The a persistent drumbeat among American liberals that in Europe austerity has failed. This is a myth. In fact, it’s never been tried.
Well, ain’t that a pisser. “‘European solidarity is not an end in itself and should not be a one-way street. Germany’s engagement has reached it limits,’ said the text, drafted by Chancellor Angela Merkel’s Christian Democrats and Free Democrat (FDP) allies.”
Has Germany’s willingness to throw bad money after good to bail out wastrel Greece’s unsustainable welfare state finally reached an end? Maybe. Or maybe Merkel is angling for more leverage over Greece to force them to cough up some more sovereignty, or even to (fat chance) actually implement austerity measures rather than just give them lip service. But without Germany, the IMF isn’t going to cough up, and without the two of them, there probably isn’t enough in the kitty to finance even the latest round of Greek bailout, much less the larger fund needed to staunch the contagion once the Greek default dominoes start tumbling.
The game of musical chairs may finally be reaching its end.
Greek bureaucrats in their Social Security office stage a walk-out. Now if all government employees went on strike and stayed there, they might just have a chance…
Want to know exactly how the Greek debt bond swaps will proceed? Me neither, but here it is anyway. Just part of full-service blogging, Ma’am….
Spain’s housing market makes ours look healthy by comparison. “Repossessed houses in Spain are valued at 43 percent less on average than the appraisals on the mortgages.”
So the latest “final” bailout is agreed upon, the Greek parliament passes the austerity measured decreed by their German overlords like good little members of the Eurocratic elite, and for their troubles Greek citizens (whose input on the issue is neither required nor desired) responded to these events with widespread arson and looting.
Here are some protesters expressing their displeasure with austerity measures via the now-traditional medium of Molotov cocktails:
Who are we supposed to root for, the Eurocrats who turned a blind eye to Greece’s spendthrift ways when they let them join the Euro, the Greek bureaucrats who went on an orgy of unsustainable welfare state spending with Germany’s credit card, or the Greek citizens who happily sucked at the welfare state teat as long as Uncle Helmut was paying for it and are now throwing a hissy fit because mean Aunt Angela wants to ween them away? It’s like trying to decide between the pusher who stops giving away free heroin after ten years, or the junkie suddenly denied their fix: There are no heroes or sympathetic actors. Keep giving me my heroin or the Acropolis burns!
Other burning Euro issues:
And those members of the Greek parliament who voted against the deal? 43 members of the socialist and conservative parties were were immediately expelled from their parties. That will teach them not to heed their master’s voice…
Those austerity measures are absolutely set in stone…except that they’re not. “Antonis Samaras, leader of New Democracy and likely the next prime minister, said the measures should be renegotiated after national elections expected in April.” What’s mine is mine, what’s yours is negotiable.
Forbes spins scenarios. If Greece leaves the Euro, things get slightly worse. All the PIIGS leaving is a bit more serious. Germany leaving the Euro? It makes the the housing bubble aftermath look like a clear blue sky of deepest summer by comparison…
As long as Germany wasn’t complaining, others could make free with Germany’s credit card. Once in the euro, Greece, Italy, Spain, and other countries that bankers used to consider reckless or unstable could borrow at the same rates. (The treaties that bound all these dissimilar countries together stipulated that there would be no bailouts for those who borrowed too much, but bankers obviously didn’t believe that.) A boom in lending pushed up wages and prices in those “peripheral” countries, rendering them uncompetitive. After the financial crisis of 2008, the countries that had overborrowed were saddled with more debt than they could comfortably repay. The eurozone’s Mediterranean members have come to think that Germany ought to rescue them. But the Germany to which they are addressing their petitions is not the penitent, diffident, and easily browbeaten land that they came to know over the last three generations. Germany has its own ideas about economics and morality, and it is ready to insist that its weaker neighbors adhere to them.
(snip)
The German public was dragged into the euro reluctantly and would never have consented to it had they been consulted. “The euro has always been the ‘Golden Calf,’ so to speak,” says Barclays’s economist Thorsten Polleit. “It was forced upon Germans.” There is still a lot of debate about how it was forced upon Germans. The most common explanation is that French president François Mitterrand insisted on the euro as a condition of Germany’s reunification. A number of Germany’s top politicians and economists assured citizens that the new currency would hold prices stable. That turned out to be right. They also promised that this would not mean sharing wealth and bailing out laggards. That turned out to be wrong—and perhaps catastrophically, apocalyptically wrong. In the late nineties, “many chief economists did a lot of client presentations where they told people the euro would be as stable as the German mark,” says Jörg Krämer, chief economist at Commerzbank. “I am quite happy I was young enough not to have had to do this.”
How the latest deal could trigger a crisis “rivaling anything yet seen.”. Also: You know which bank isn’t taking any haircut at all he latest debt deal? The European Central Bank.
Greece and the EU are having their final showdown (I tell you final! This time we mean it! Lather, rinse, repeat!) over the Greek debt crises. Until they do it all over again two months from now.
Some people wonder just what all this has to do with the U.S. economy? Well, the one good thing about having a crack house at the end of the street: No one worries about how crappy your own house looks, because it’s great by comparison. But once the PIIGS start defaulting, getting kicked out of the EuroZone, or both, people are going to start to notice that Obama hasn’t mowed the lawn in months…
Metaphors! I mix them! Now back to all that exciting Euro-defaulting action:
Europe tells Greece take the deal or else. Of course, as Bob Dylan once noted: “When you got nothin, you got nothin to lose.” At this point, who does throwing Greece out of the EuroZone hurt worse: Greece, or Europe? Alternate metaphor: Maybe you should have cut off that gangrenous toe before it spread to your thigh…
And what’s this unacceptable demand Europe is making? To cut deficit spending by…1.5% of GDP. For a country running a deficit of, what, 9% of GDP? “Son, you’ve got to promise you’ll cut down on shooting smack by one-sixth.” Hey Greece (and, for that matter, Europe. And Obama): How about you (and try to keep up with me here) stop all deficit spending? That would take care of the problem, no?
The real reason Germany is asking for total control of Greek finance in exchange for the next bailout? To make Greece say no so they don’t have to bail out the rest of the PIIGS: “How do you preclude Portugal, Ireland and, indeed, Spain from asking for the same deal as Greece, if the negotiations succeed? Answer; you can’t. So the Germans throw a politically impossible demand in front of the Greeks, in effect saying, “No more money unless you effectively surrender your national sovereignty.” And that’s the implied warning ahead for the other periphery countries which look to secure the deal currently on the table for Greece. In effect, the Germans (behind the auspices of the troika) are saying, “It’s fiscal austerity on our terms. You try to renegotiate like the Greeks and we take you over. The other alternative is that you leave.”
This article goes into detail about how exactly they lied.
The leader of the Greek Coalition of the Radical Left says the EU won’t dare kick Greece out. And he also wants a three-year suspension of all payments by Greece to foreign creditors. He may be on to something. When you owe the bank $3,000, you have a problem. When you owe the bank $30 billion, the bank has a problem. The OJ Simpson/Clevon Little technique of holding a gun to your own head just might work. “Do what he says! He’s crazy!”
Spain’s fourth largest airline collapses. “The airline was seen as a flagship of the regional government of Catalonia, which had helped it stay afloat with more than 150m euros of subsidies. The government refused to provide more funding on Friday.”
You know the problem with doing one of these roundups on the European Debt Crises? I can search for “Euro” just about anytime of the day and night on Google News and come up with a dozen things I could potentially include. So just consider this a Whitman’s European Despair Sampler of possible bad news, as there’s a lot more where this came from:
European Finance Minsters on Greece’s latest bond offer: REJECTED.
In exchange for bailing out Greece yet again, Germany wants Greece to cede control over its tax rates and budget to an EU commission (i.e., Germany). It’s almost touching, this German naivety that Greeks can actually be compelled to obey German laws when they can’t even be compelled to obey Greek laws even now. But despite the fact that such government dictates would be ignored just like they are now, Greeks are still furious at the proposal. (Hat tip: Ace.)
And if Berlin doesn’t get to call the tune? “Germany and the Netherlands are likely to quit the eurozone rather than swallow an indefinite number of ‘unrequited transfers’ to the union’s crisis-stricken nations.”
What will European currency look like after a Euro-zone breakup? Like this.
Another month, another EuroZone bailout fund. The rules for the New and Improved Euro Bailout Fund is: 1. “Access [will] be made conditional on signing a new treaty on fiscal discipline.” 2. “Countries representing 85 percent of the fund’s capital [will make] decisions instead of unanimity among the eurozone 17 – will only apply to authorise ESM loans from existing funds.” So 1.) We get an entire new set of fiscal discipline guidelines for the PIIGs governments to ignore, and 2. Germany will call the tune, and the rest of the Eurozone will dance. At least until the next shuffling of the fiscal deck chairs.
Well, here’s a headline sure to fill investors with confidence: “From now on, in Europe, everything gets worse.”
Spanish unemployment hits 23.4%. And what happens when austerity means they can no longer pay people not to work? That’s he problem with cradle-to-grave European welfare state: sooner or later you run out of your grandchildren’s money…
The Soviet Union yesterday: “We pretend to work, and they pretend to pay us.” Greece today: “The old dynamic—with Greece pretending to make structural changes and its lenders pretending to save it from default—has become untenable.”
The whole EU illusion has been predicated on the assumption that Greeks can be made to behave like Germans, and that the EU could manage to forge a new, multi-ethnic, post-national identity in 20 years when Belgium hasn’t been able to do it in almost 200.
Cameron caves. Sadly, this behavior is far more in line with his previous record than his brief stint of standing on principle.
House Republicans are working to rescind the $100 billion IMF bailout fund Nancy Pelosi helped create. They may not succeed, but they might force the Obama Administration to defend backstopping the Euro at a time when the federal budget is still hemorrhaging red ink…
Last week: France’s credit rating makes our latest Euro bailout fund rock solid. This week: oops.
The threat of default is also holding up the merger of two Greek banks, maybe because it’s as yet unclear just how they’ll put European taxpayers on the hook for their losses. Once that’s figured out, I’m sure the merger will fly through…
Those bondholders who can’t stick it to taxpayers are looking at 70% losses for Greek debt.
The race to a Euro-crackup seems to have slowed down to merely a jaunty saunter this week. Maybe once everyone made it to the New Year without a sovereign default, the Eurocrats might have breathed a sigh, confident that there’s still a few miles yet before they went over the falls…
Germany could create a parallel currency—a new D-Mark, pegged at 1.0 to the euro. The German government would guarantee that holders of German government bonds could convert euro securities to new-D-mark instruments on a one-to-one basis up to some designated date, perhaps two years in the future. Private German contracts expressed in euros would switch to new-D-mark claims over the same period. The transition would likely feature a period in which the euro and new D-mark circulate as parallel currencies.
Other countries could follow a path toward reintroduction of their own currencies over a two-year period. For example, Italy could have a new lira at 1.0 to the euro. If all the euro-zone countries followed this course, the vanishing of the euro currency in 2014 would come to resemble the disappearance of the 11 separate European moneys in 2001.
Of course, this would mean that any bonds from the PIIGS with a maturity date more than two years in the future would trade at a heavy discount, but that’s far preferable to the looming Euro crash. But a bigger problem to this proposal actually being implemented is that it reverses the drive to centralize European bureaucracy, and Eurocrats will never stand for that.